Hotels & hospitality
Guest rooms, busy lobbies, and everything that keeps a property running.
Start a review Explore hotel insurance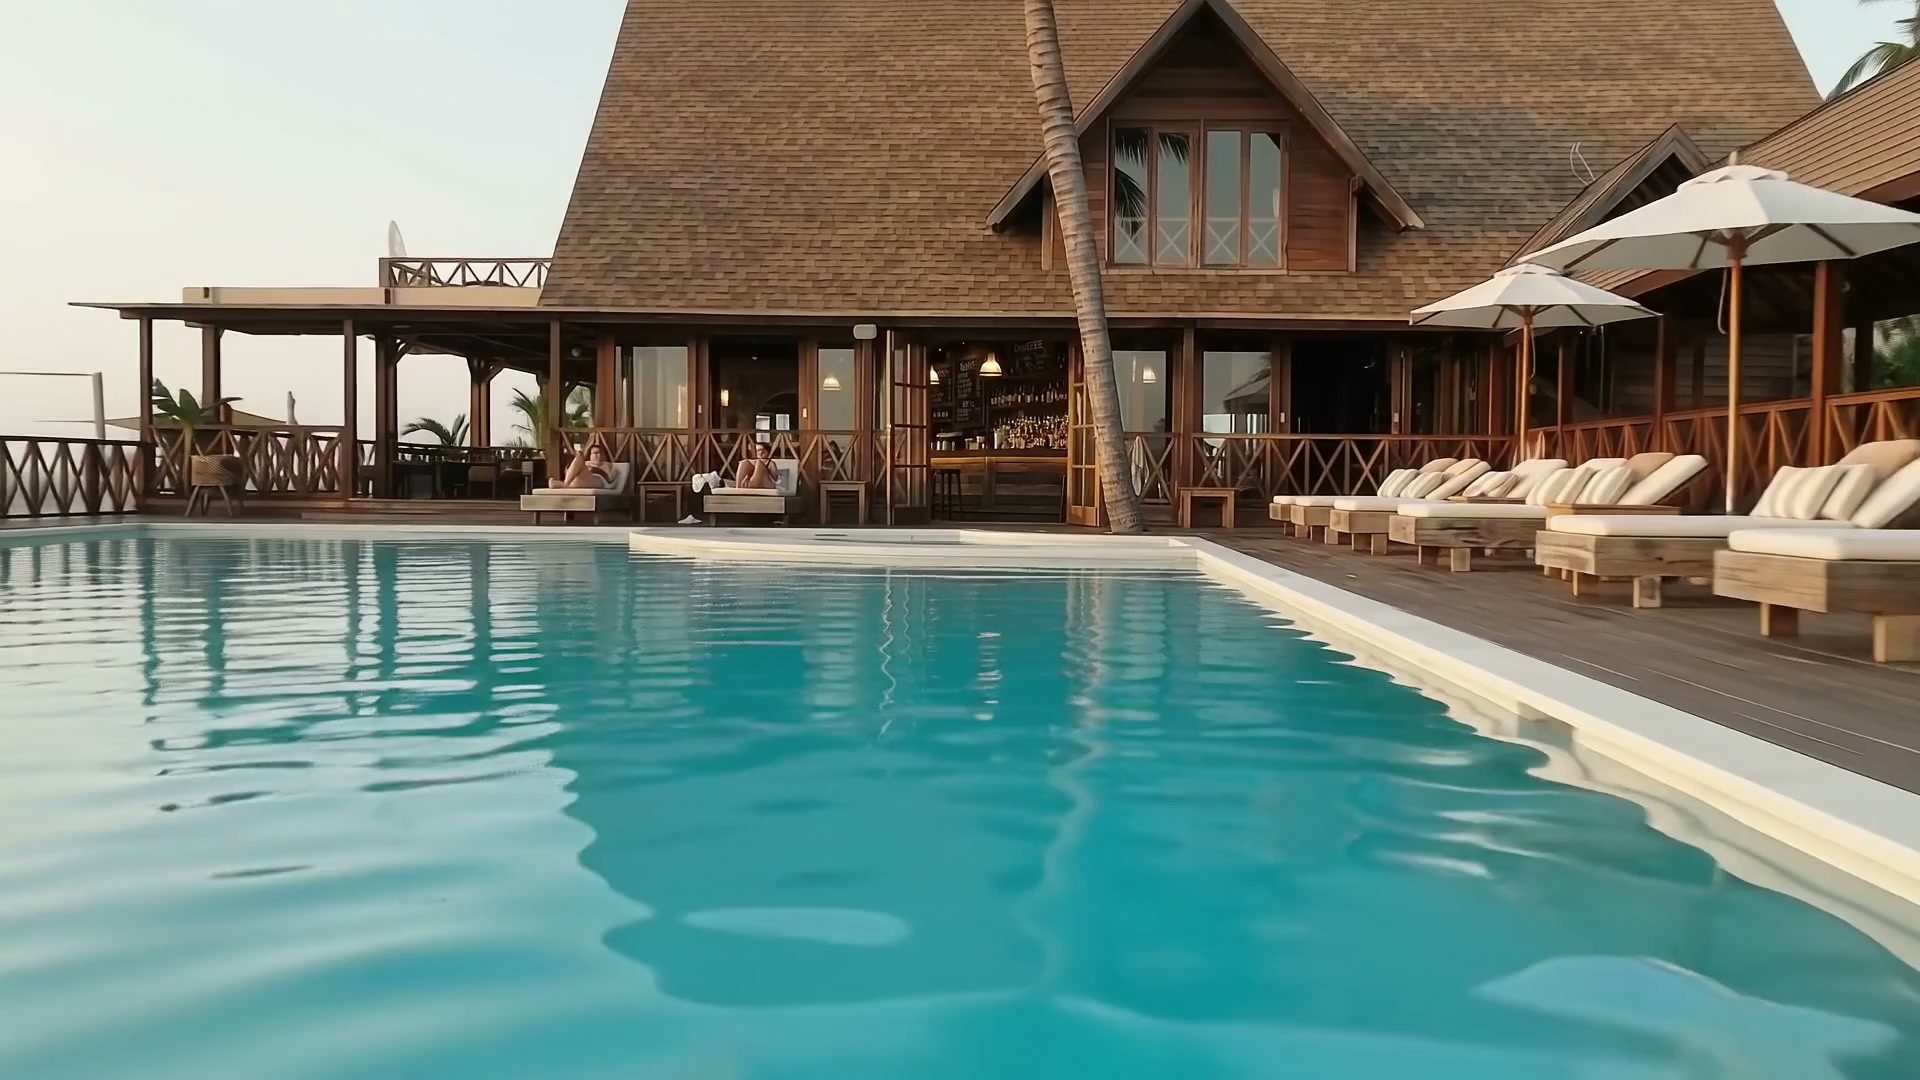
Turner Lacaze helps hotel, restaurant, and hospitality owners get the right coverage at the right price, without the runaround.
Get Your Quote01 Hotels
Turner reviews your hotel’s property coverage, guest liability, and business income protection.
02 Bars
Turner reviews liquor liability, security requirements, and exclusions that could affect your bar’s coverage.
03 Restaurants
Turner reviews coverage for your restaurant’s equipment, employees, and interruptions to service.
Your insurance advisor
Turner is a licensed producer with Maury, Donnelly & Parr. Based in Charleston, helping hospitality businesses nationwide.
Personal guidance from Turner.
Backed by Maury, Donnelly & Parr.
Selected commercial carriers

Built around your business
Hotels, restaurants, and hospitality businesses carry distinct risks — liquor liability, property exposure, guest injury, and business interruption. Start with the way your business actually operates.
Guest rooms, busy lobbies, and everything that keeps a property running.
Start a review Explore hotel insuranceFrom the first delivery to the last table. Coverage for your kind of service.
Start a review Explore restaurant insuranceBuildings, tenants, and the income you depend on. Start with a property review.
Start a review Review your propertyA considered approach
You bring the business. Turner brings the questions worth asking.
Share your operation, location, and renewal date. The short form gets the conversation started.
Turner looks at your exposures and existing policies, then explores suitable coverage options.
Understand limits, deductibles, and trade-offs before deciding. Coverage is confirmed by a licensed specialist.
 Rooted in hospitality.
Your advisor
Every property has a story. Every operation has its own details. Turner takes the time to understand yours before exploring what comes next.
A starting point for your review. Coverage depends on the policy, its limits, conditions, and exclusions.
The building, kitchen, rooms, and equipment, valued at what replacement costs now.
Guest injury and everyday premises risk — the base layer every hospitality program sits on.
Extra limits above general liability, liquor, and auto, for the one claim that outgrows the base policy.
Alcohol service is usually outside a basic general-liability form. Bars and dining rooms need it named.
Cards, reservations, and POS outages. A weekend of online orders is a data event, not an IT footnote.
Housekeeping, line cooks, and front desk classified correctly so payroll is not guessed at renewal.
If the property cannot operate, the indemnity period and values have to match how it actually earns.
Private events change who is on site and who must be named. Turner flags that before the first toast.
Beyond hospitality, Turner also helps with auto and fleet coverage and personal insurance, including home, auto, and umbrella. Ask about your other insurance needs.
A few things owners ask us. None of this binds coverage or quotes a price.
Restaurants, bars, nightclubs, hotels, breweries, event venues, caterers, food trucks, private clubs, and other hospitality businesses.
General Liability, Property, Business Income, Excess Liability, Workers Compensation, Liquor Liability, Cyber Liability, Employment Practices Liability, and Commercial Auto/Hired & Non-Owned Auto.
Usually not. Businesses that sell or serve alcohol generally need to make sure their insurance program specifically provides Liquor Liability coverage.
Restaurants that process credit cards, store customer or employee information, offer online ordering, or rely on computer systems should consider Cyber Liability coverage.
Yes. Turner can review the insurance requirements in your lease and discuss the coverage, limits, and endorsements to check with your carrier.
Often, yes. Multiple locations can potentially be insured under the same insurance program, although each location should be properly scheduled and its exposures disclosed.
Timing depends on the complexity of the business and the information available. Providing complete information upfront — sales, payroll, property values, alcohol sales, prior coverage, and loss history — can help the review move forward. Turner will discuss the expected timing with you; carrier responses vary.
Restaurants, bars, hotels, and venues face exposures that aren't always obvious — from liquor liability and assault & battery to spoilage, equipment breakdown, business income, cyber, delivery, and contractual requirements. Turner reviews those exposures with you and explores suitable options with the account team and carriers.
Yes. Our role doesn't end when the policy is purchased. We help you navigate the claims process, communicate with the insurance company, and understand what information is needed to move the claim forward.
Yes, I can help with all types of commercial insurance and personal insurance including home, auto, umbrella, jewelry, watercraft, etc.
Start a conversation
Fill this out and Turner will follow up personally.
Prefer a conversation? or call 854.444.8290.